 Phoenix Court
How we'll find growth in every postcode
Restoring confidence in the UK economy starts with knowing where the growth is coming from. With the Budget announced this week, Nin Pandit explores the opportunity to capitalise on innovation that already exists around the country.
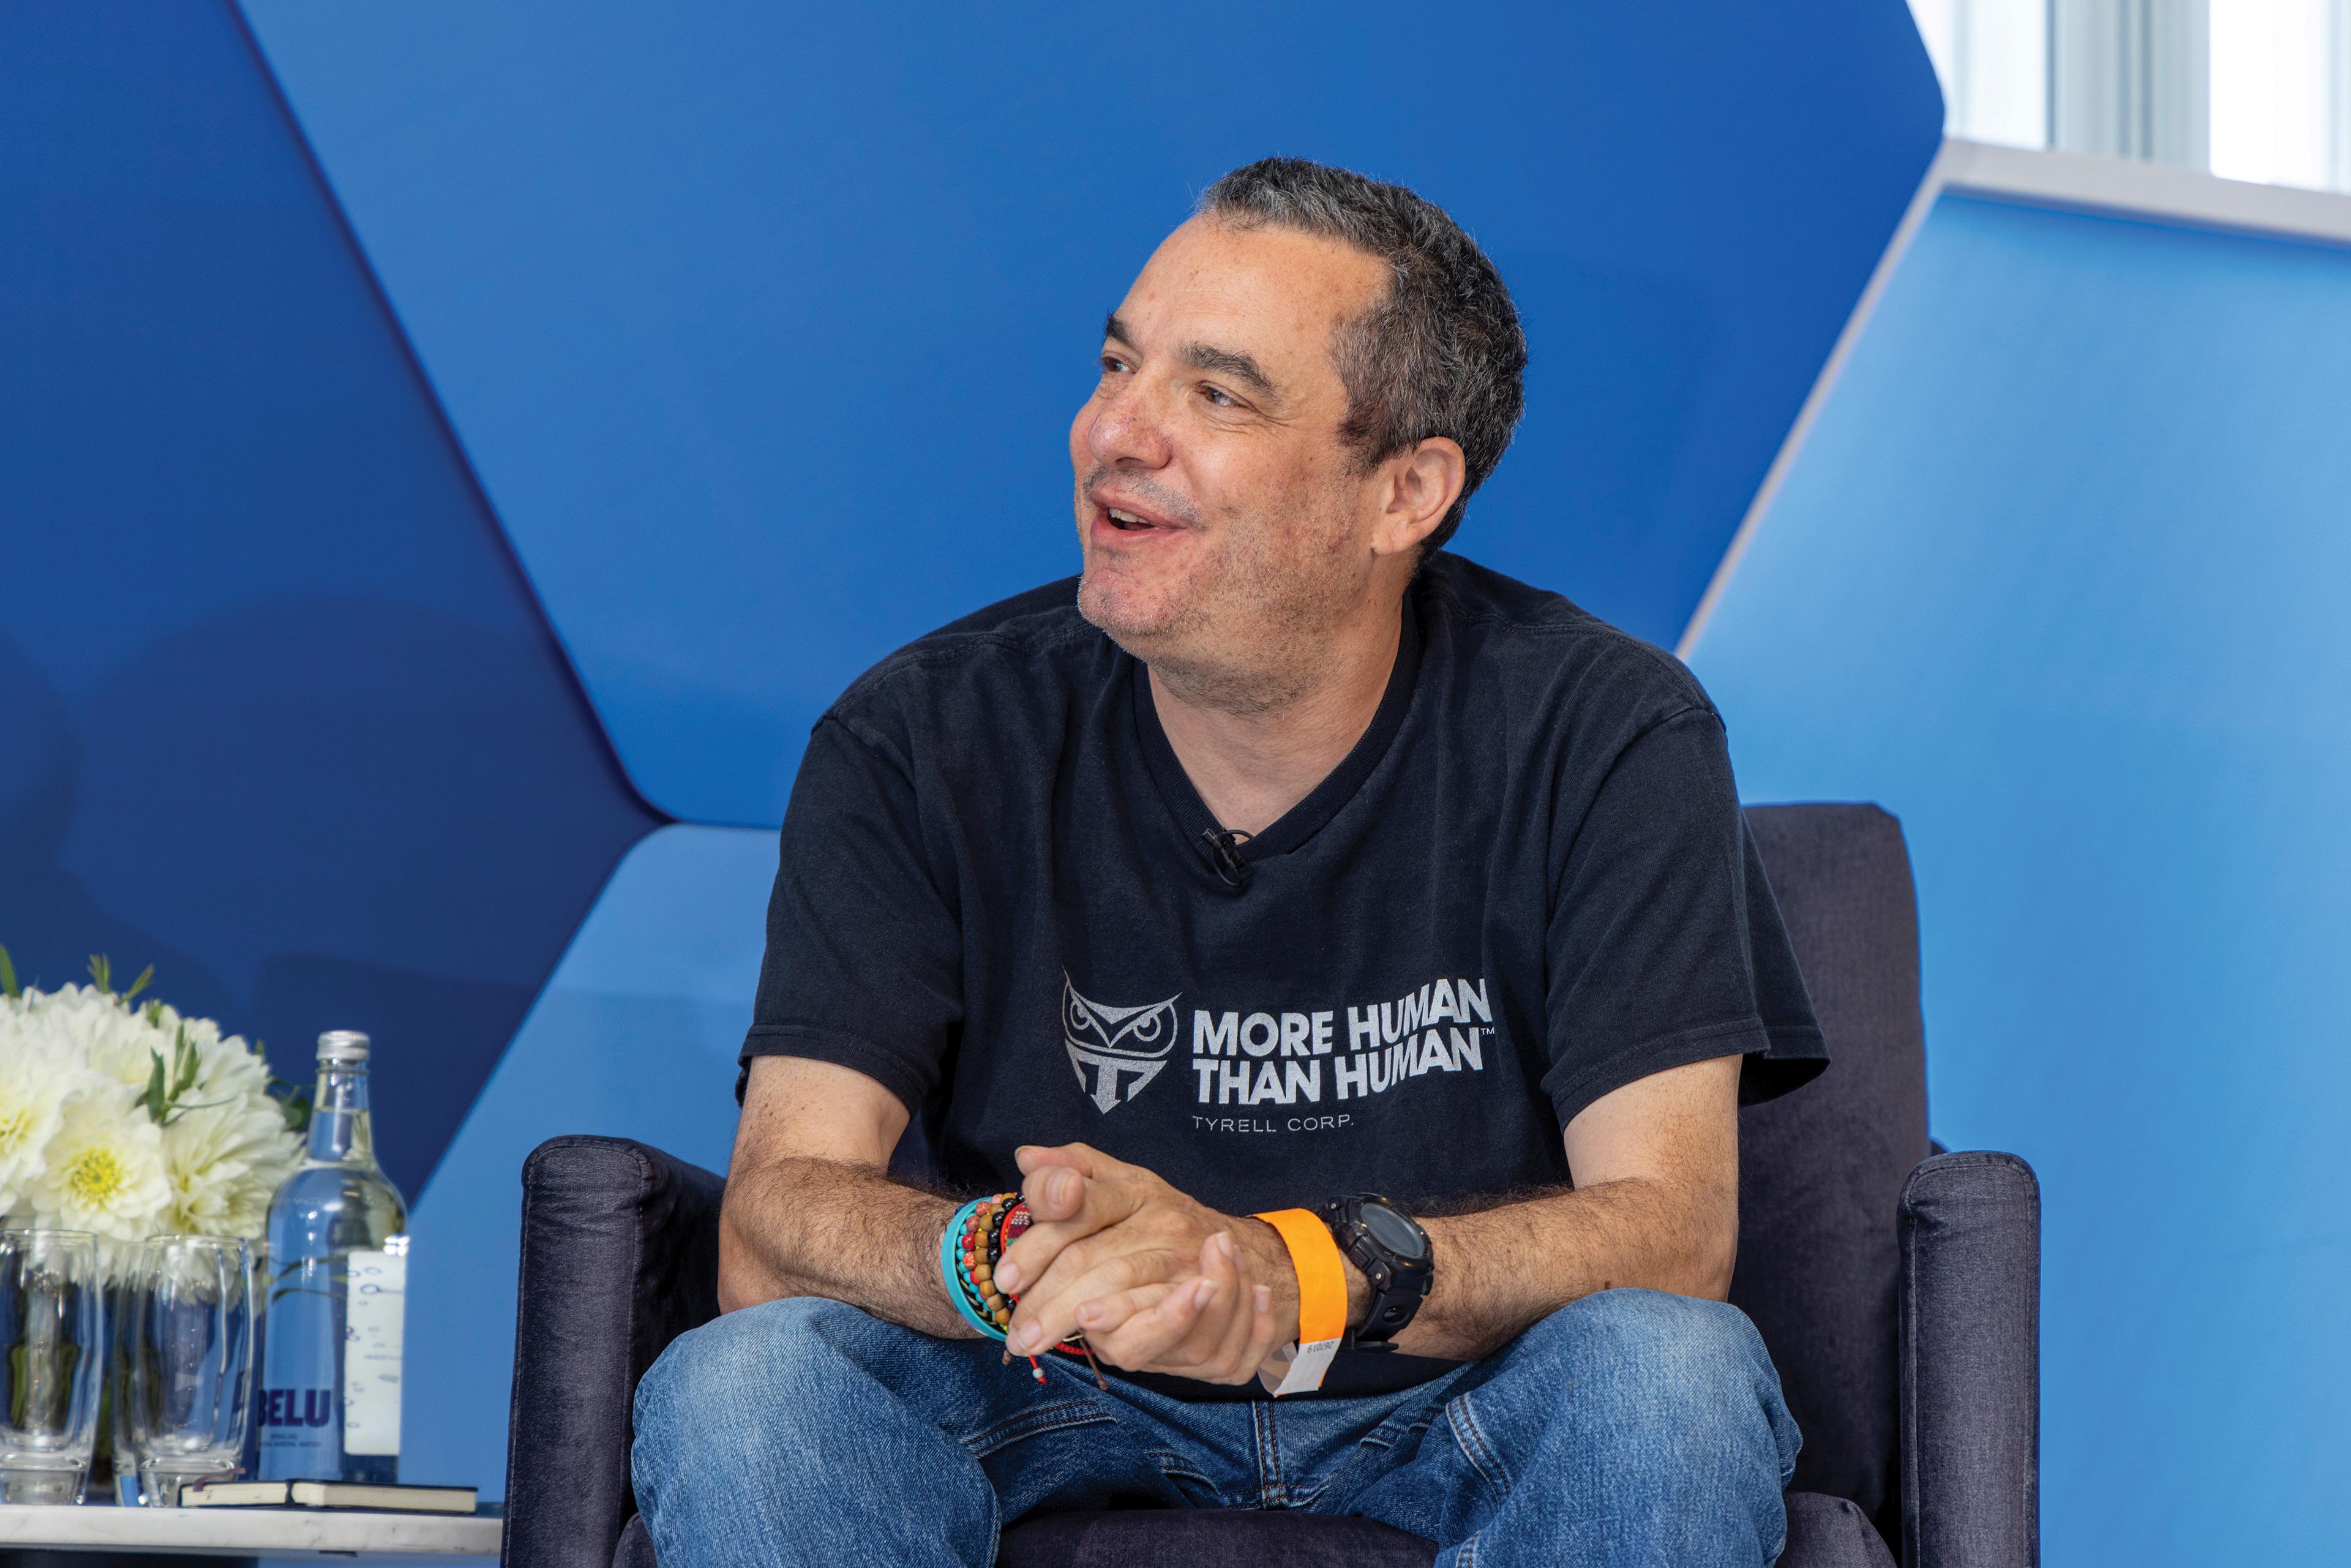
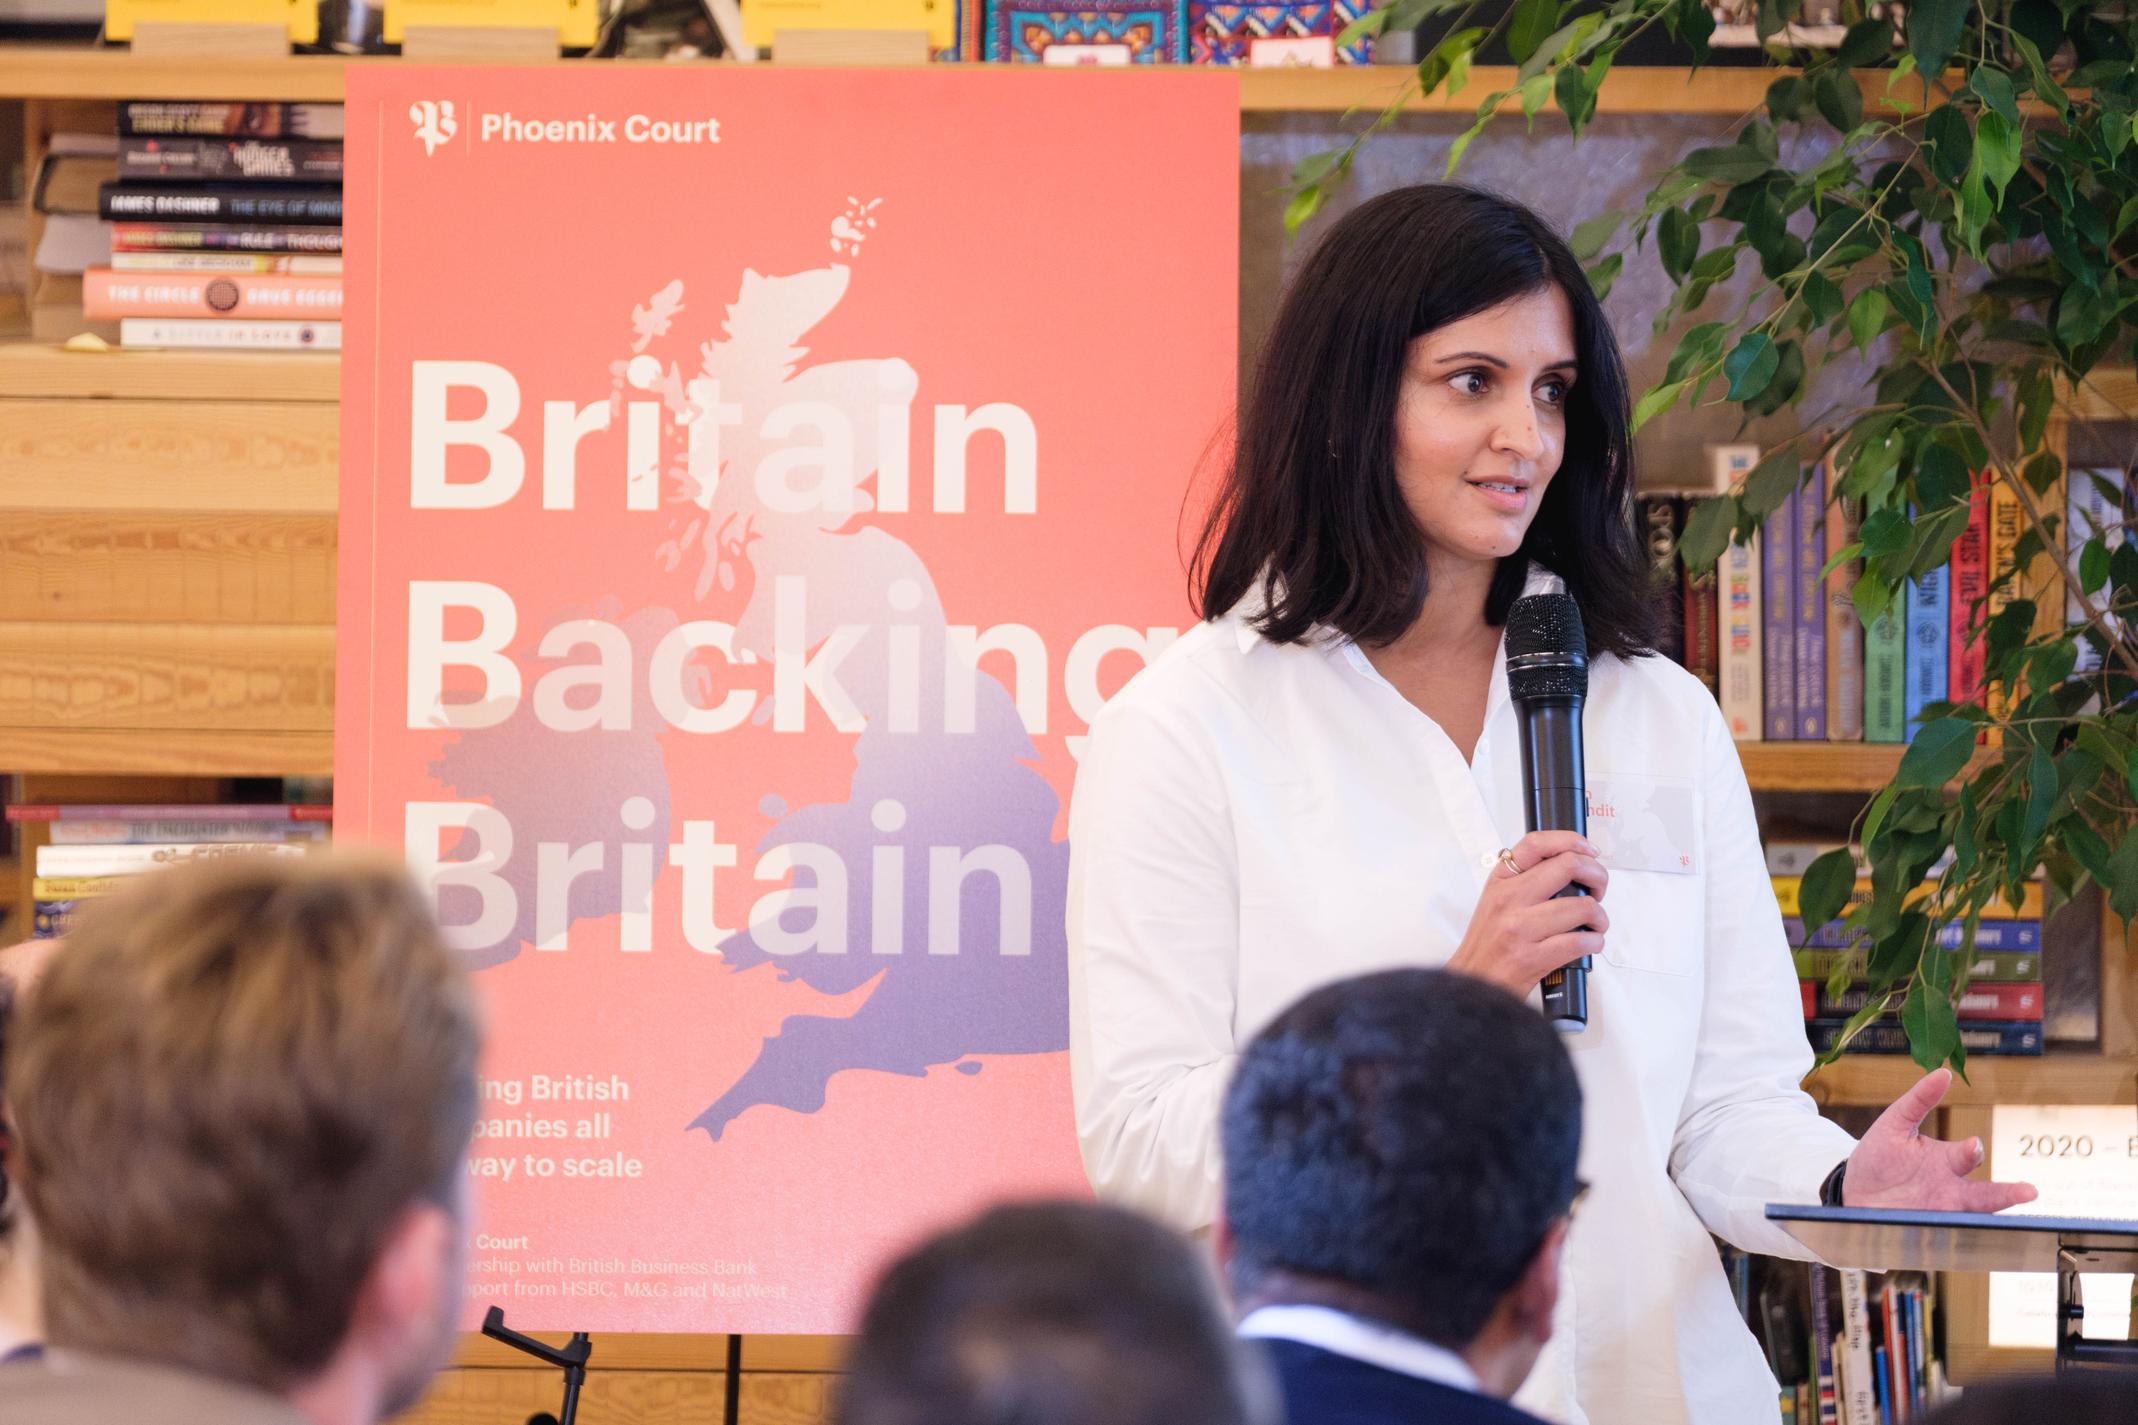 Nin Pandit, Phoenix Court's Managing Partner for Value Creation, speaking at our Britain Backing Britain event in September
Notts County Football Club’s glory days are a distant memory.
At over 150 years old, the Midlands outfit is the oldest professional football club in the world. And yet you have to look back over a century for its last major trophy, when they lifted the English FA Cup in 1894. That early taste of success has rarely returned, as the club has mostly floated between the lower tiers of English football.
Its Meadow Lane stadium sits at the heart of one of Nottingham’s most deprived wards, Meadows ward, where close to a third of children live in poverty. A community built on textiles, bicycle engineering, and pharmaceuticals, congregated around a once-great football club.
It seems incongruous that this same council is home to a group of companies with over $1.4 billion in revenue. 10 Colts ($25M+ revenue) and 1 Thoroughbred ($100M+ revenue) with venture backing sit just a stone’s throw from the club, including the $900M+ revenue Games Workshop (behind the popular game Warhammer). Notts County is not alone. Over 90% of the football clubs in the top four leagues in England have a Colt or Thoroughbred in the same council.
Data like this defies the dominant narrative that the UK’s innovation economy is focused almost entirely in the Golden Triangle between London, Oxford, and Cambridge. Political appetite in recent months has focused on achieving “growth in every postcode”, a motif that featured at the centre of the recent Budget announced by Chancellor John Healey.
This points to a disconnect between aspiration and reality. On the one hand, economic activity is already far more distributed than you might expect through pockets of innovation, not just in Nottingham but all around the UK. Our data shows that 8 in 10 people in the UK live in a council with at least one Colt or Thoroughbred.
And yet, the effects of this growth are rarely felt by the communities in every postcode. That a $1BN revenue cluster can sit astride socio-economic deprivation reveals an opportunity to make local revenue do far more to drive economic returns and improve living standards locally. We see this close to home in Somers Town, where the rapidly-growing innovation hub of King's Cross sits minutes away from one of London's most deprived neighbourhoods.
In light of the recent Budget, and conversations we had around our recent Britain Backing Britain gathering, we’re interested in understanding how the UK can capitalise on its position as the world’s third largest innovation economy in a way that benefits all stakeholders.
It’s a double headed challenge, one which addresses not only the reality of where our growth comes from, but also with regard to our confidence to capitalise on opportunities that lie in our lap.
The reality of regional innovation
The perception that innovation is concentrated in the south is reinforced by funding statistics: the Golden Triangle accounts for around 85% of all venture capital funding. London accounts for around 22% of UK GDP, and yet attracts 75% of venture capital.
There are structural reasons for this. The vast majority of VC funds (close to 80%) are based in London, making proximity a critical factor when it comes to investing. That, on top of the concentration of financial services, AI, media, and software activity in the capital making it a pretty attractive pool for VC investment.
“Colts and Thoroughbreds currently sit in 105 of the UK's ~121 postcode areas.”
The emerging narrative around reindustrialisation, which featured at the centre of the October Budget, doesn’t fit neatly into a traditional venture lens that is typically far more comfortable with digital technology. Take aerospace, where the UK industry is among the world’s largest. The Chancellor nodded to this by announcing a £2.5BN joint 10-year aerospace programme between Rolls Royce and the government to develop next-generation gas turbine technology for civil and defence applications.
Whether it’s Airbus near Bristol or Rolls-Royce in the Midlands, why are these industrial clusters only just beginning to register with VCs. There are similar examples of photonics in Southampton, automotives in Sunderland, nuclear in Sellafield, life sciences in Macclesfield and Darlington. Major hubs that traditionally sat outside the standard venture scope but carry real industrial weight for the UK.
We’re seeing examples of industrial activity falling between jurisdictions, a result of when economic activity doesn’t fit neatly into council or combined authority lines. One case is in Liverpool, whose strategy and investment cover its own six boroughs but excludes BAE Systems in Preston and Airbus’s wing factory in Broughton (just over the border in Wales). An economic plan that misses this huge aerospace and manufacturing economy, or other between-jurisdiction industries, are both misrepresentative and a missed opportunity. As power becomes more greatly devolved, especially through Mayoral Strategic Authorities, the risk is that these lines become more firmly drawn.
The third challenge is one that is found across all forms of investment, that all too often, overseas investors are far more bullish on British companies than our own investors are. Sportswear retailer Gymshark is just one of many examples of this: a Birmingham-born bootstrapped business that had to go to the US to raise its first capital. It’s now valued at over $1.5BN, and did over $860M revenue last year. But this is growth that whose benefits are being largely felt by the international investors bold enough to back it, rather than those back at home.
It's not just private companies that do this, it's the UK government too. Public procurement processes have often seemed to naturally favour overseas firms. For instance, our ambitions to become an AI superpower are undercut by the finding that 69% of AI procurement value goes to overseas or foreign-backed suppliers.
Clusters, contracts, and talent
Conversations with our network and at our Britain Backing Britain event have surfaced a number of ways to redress the imbalance of regional growth and investment.
We've seen the power of clusters as an instrument for investment and regional growth. The network effects of proximity enables companies to attract the sort of talent and funding that would be much harder in isolation. It’s also often the case that these resources are absorbed by the ecosystem even if companies fail. With reindustrialisation firmly on the agenda, this could prove critical.
Take Harwell, near Oxford, which formed around the UK’s former post-war nuclear research programme and has turned into one of Europe’s leading space clusters. Satellite manufacturer and operator Open Cosmos, who we’ve backed through LocalGlobe and Latitude, are at the centre of this ecosystem and are just one of the leading companies attracting top space engineering talent to the Oxfordshire countryside. They’ve even retrained workers from other industries (automotive, healthcare) for space-qualified roles.
Humber and Teesside in the North, meanwhile, is a fast-emerging hub for energy and net zero industries, building on a former industrial area (iron, steel, and chemical manufacturing) that accounted for nearly 50% of industrial cluster emissions. The project will support an average of 25,000 jobs a year between 2023 and 2050.
In both clusters, and the many others that exist around the UK, we see two clear examples of reindustrialisation bringing jobs, investment, and growth to all corners of the country.
“8 in 10 people in the UK live in a council with at least one Colt or Thoroughbred.”
It’s also worth considering the secondary effects of talent clusters, such as on entrepreneurship. University spinouts have a built in route for creation, so commercial spinouts should have the same. A senior engineer leaving Rolls-Royce with a concept needs a technology transfer office, standard terms, and access to specialist funds that understand the sector. Dedicated funds, such as the British Business Bank’s £100M aerospace supply chain fund, will go a long way to priming this sort of activity while also helping close the funding gap for resource-heavy industries.
Capital is only half the equation. For companies across the country, the hardest step is landing a first major contract. Government stepping up as that customer could do more for growth in every postcode than anything else. The Chancellor indicated support for making the first customer of UK innovation, with a new definition of ‘UK supplier’ that could tilt public spending toward firms that create jobs here. For promising companies, a government contract promises revenue, a signal of credibility, and spend that will stay in that region. We’ve embedded this work into what we’re doing at Phoenix Court, building an opportunity-matching tool to connect our companies to over £400BN of UK government procurement.
Access to growth in every postcode
The criticism of “growth in every postcode” makes the mistake of thinking it's a binary choice to either capitalise on established ecosystems or to invest in building new ones.
For one, this fails to recognise the existing breadth and depth of Britain’s innovation economy, particularly with regard to harder industry. Colts and Thoroughbreds currently sit in 105 of the UK's ~121 postcode areas. But more importantly, it ignores the ambition that better regional investment would both add to agglomeration across the UK, while also contributing to growth in core venture centres.
Perhaps a more pressing test is whether people in every postcode can access growth opportunities. On this ground, we start from a strong position: colts in councils where over 80% of people live, innovation clusters from Aberdeen to Southampton and from Plymouth to Middlesbrough.
What’s missing is a link between growth and the communities who stand to benefit from it. Three things could start to build this link. Firstly, shifting a wider investment lens to include industrial sectors outside of the Golden Triangle where Britain has the opportunity to lead, and to fix the scope which means regional governments miss supply chains that cross their boundaries. Secondly, by bolstering the demand side for these companies through channelling procurement opportunities towards the British companies best suited to meet them. And finally, making sure that growth is felt. Ensuring that capital and revenue impacts the streets outside, tying growth to jobs, local skills, and further innovation and entrepreneurship.
For football clubs like Notts County, current fortunes remain uncertain, and on-field success may remain a remote possibility for the near future. But for the innovators, companies, and communities around them, the path to success may be clearer than we think.
Related reading
19 Oct 2026 — editorialWritten by Phoenix Court
The Three Clock Speeds
At our Annual Showcase 2026, five companies shared experience from building across vastly different paces and timeframes.
2 Oct 2026 — editorialWritten by Phoenix Court
$5.5BN+ raised. Reflections from one of our biggest quarters to date
From robotics to cutting edge biocomputing, from outer space to inner creativity: Q3 2026 was our busiest summer in memory.
23 Sept 2026
British Business Bank commits £50m to Phoenix Court as NatWest joins M&G and HSBC to back platform investing in Britain's scale-ups
Institutional investors join forces to ensure more of the value created by UK innovation benefits Britain Meaningful multi-year partnership across Phoenix Court’s platform, supporting British technology companies across…
22 Sept 2026Written by Saul Klein
Why Britain needs to back Britain
As a serial entrepreneur, operator and investor I’ve noticed that Britain has a habit of talking itself down, even when the evidence tells a different story. Across the…