 Phoenix Court
$5.5BN+ raised. Reflections from one of our biggest quarters to date
Written by Phoenix Court
2 Oct 2026 — editorial
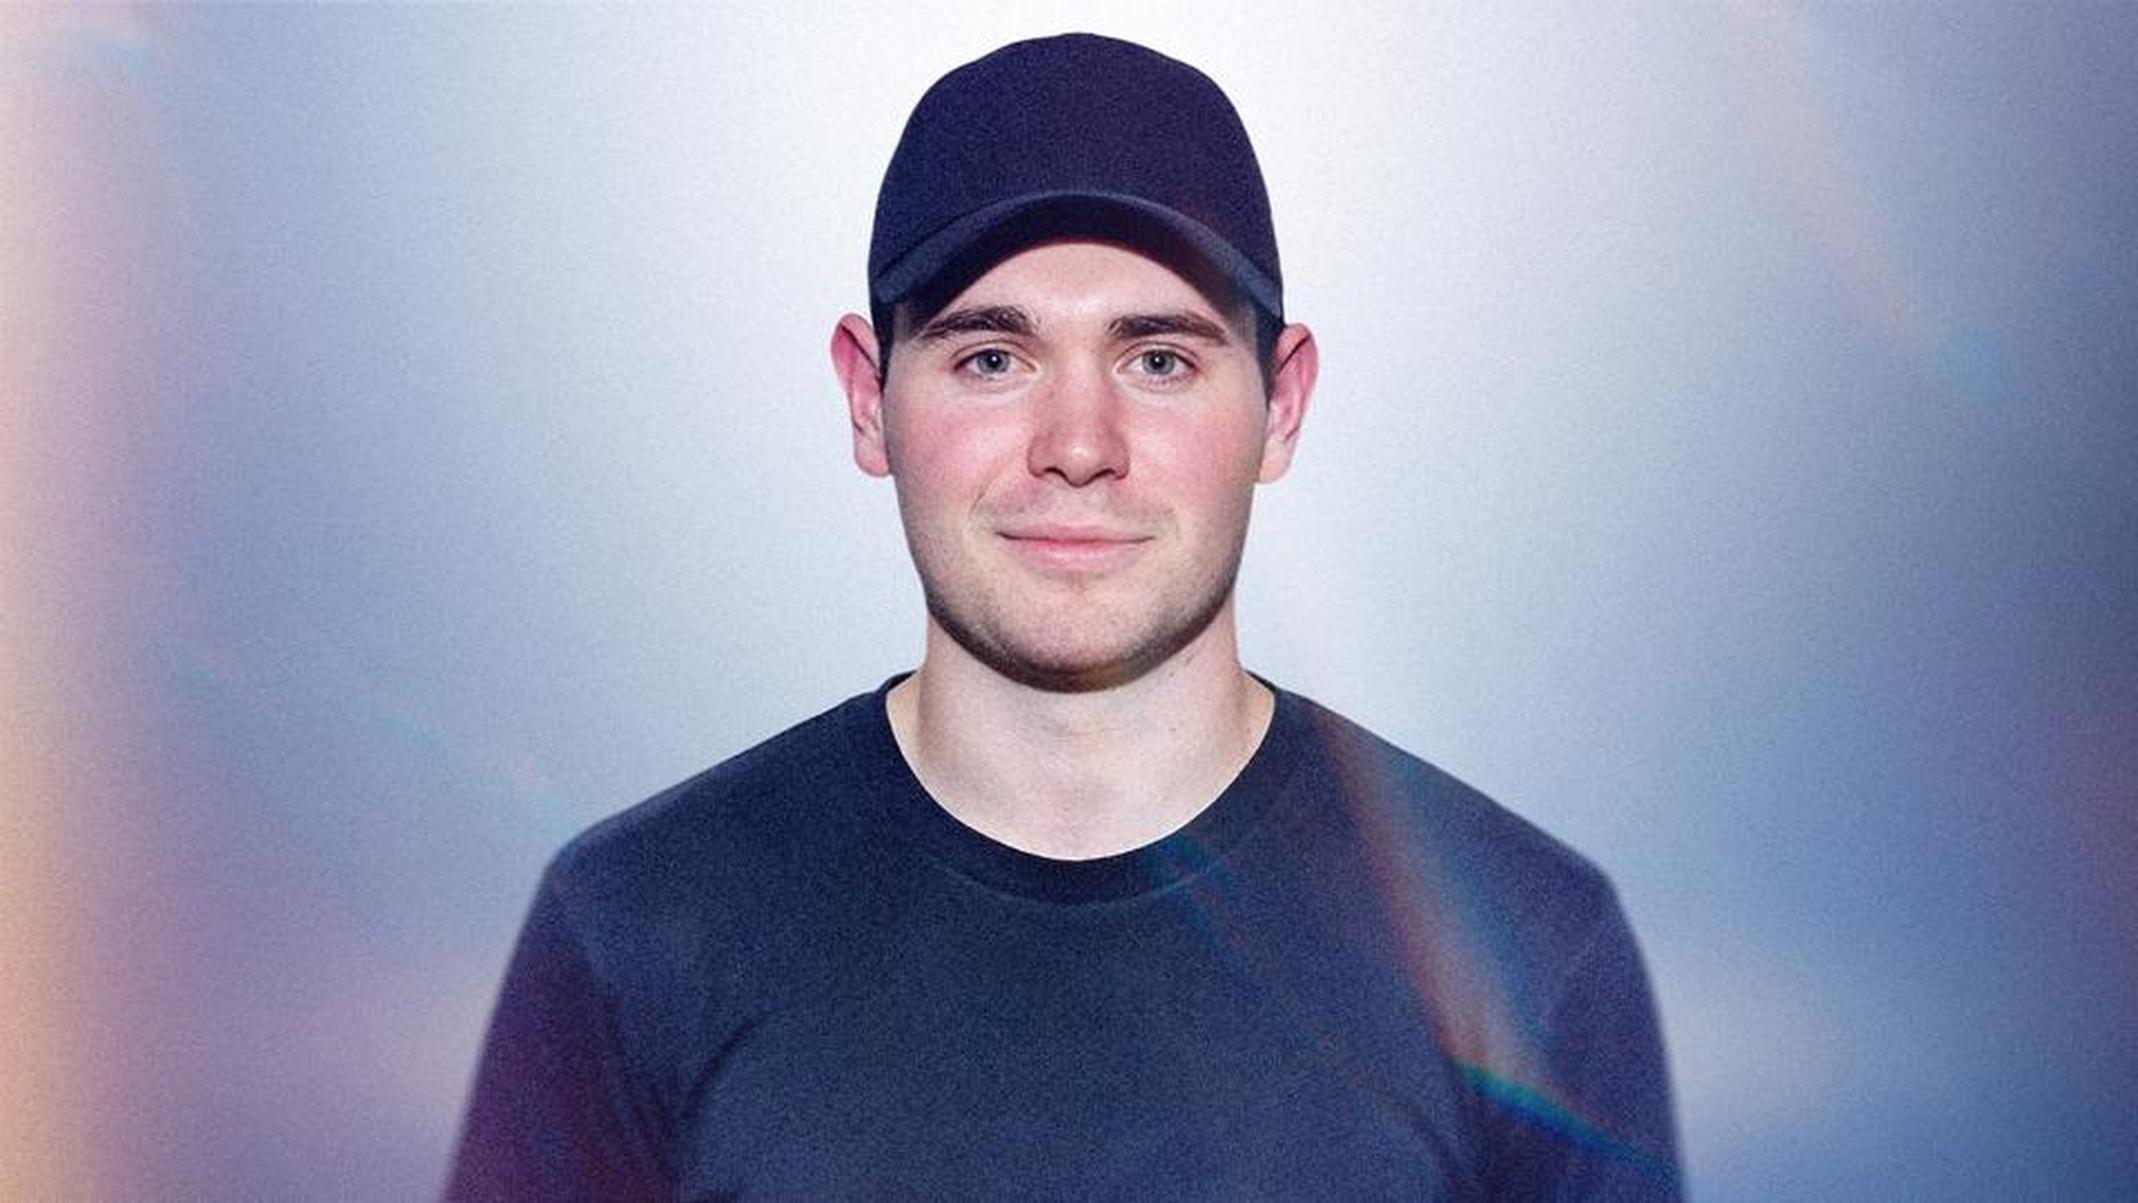 James Dacombe, founder and CEO of OLIX, who raised $312M in August for new specialised silicon infrastructure for AI inference.
Summer may now feel like a distant memory as the grip of autumn takes hold. But this year, things feel different. Did that European slowdown in July and August ever arrive?
Is the myth of the European summer finally over?
At Phoenix Court, we witnessed one of our biggest quarters to date from a portfolio fundraising perspective. In Q3 alone, our portfolio brought in over $5.5BN in funding. From multi-billion dollar growth rounds to promising pre-seeds, from outer space to inner creativity, here are some of the highlights of Q3 2026 and what we’ve learned in the process.
1. Europe is building its own AI stack
We’ve become accustomed to the global reverberations that emit when a new landmark LLM is launched, just like when Anthropic released its Fable 5 model to the world this June. But those reverberations turned to echoes when, just a week later, the US firm switched off access to anyone outside of the country.
In Europe, cries for AI sovereignty have never felt louder, as the continent’s need for its own AI stack moved from desirable to urgent. But in defiance of the cynical narrative that Europe is slowing progress in the AI race, Q3 showed signs of Europe’s AI stack taking shape.
Take OLIX, founded by James Dacombe and who are building new AI inference infrastructure based on specialised silicon and a connecting optical network. The King’s Cross-based company raised a $312M Series B in August.
Frontier Computing, who we backed at pre-seed in September, is moving away from silicon and betting on biological neurons as a new substrate for compute. The technology is proven, but the scale they’re building it on is not, until now. By January 2027, Frontier will launch its 500M biological neurone cluster, 2500x larger than the next-largest publicly available biocomputing system.
Mistral has established itself as Europe’s leading sovereign AI stack, raising €3BN in September. But this year, their focus concentrated around deployment, helping apply their proprietary frontier models into the heart of European industry.
Mistral’s Parisian neighbours ZML are building an inference server that allows models to run on any hardware: removing the friction that enterprises experience when switching between hardware and LLMs for different tasks. The implications of this are huge, in theory enabling a new generation of hardware and software “challengers”, many of whom are likely to emerge from inside Europe. Founded by Steeve Morin, they launched their latest model in July alongside a $20M raise.
At the application layer, CuspAI is realising founders’ Chad Edwards and Max Welling’s remarkable vision to accelerate the discovery of new materials using AI. Headquartered in Cambridge and with a team now spread around Europe, Cusp’s breakthroughs have strong implications of their own for Europe’s AI stack. The ability to decouple material demand (for AI inference, say) from the global supply chain is transformational.
2. Funding is betting on alternatives to existing infrastructure
With Europe’s digital sovereignty front of mind, Q3's funding reflects a growing appetite for challengers and disruptors to existing infrastructure, and most importantly, to solve its inefficiencies which stand to hinder further progress.
This language is written into the very fabric of many of our portfolio companies who have raised in Q3.
ZML says it wants to "decouple AI workloads from proprietary hardware." OLIX pitches itself as an inference alternative to the current “one size fits all” approach.
Mistral, who are still mostly concentrated in Europe, wants to "fully rely on capacity that we are building ourselves." And at the early end, Frontier wants to replace silicon entirely by looking at a frontier technology now proving itself at commercial scale.
Four companies making the same argument from different angles.
3. The physical AI revolution has arrived
2026 was predicted to be the year physical AI flourished, a result of falling technology costs and software breakthroughs that could see AI realised in the real world. From robotics transforming the factory floor to autonomous vehicles revolutionising mobility, we’ve seen strong evidence of this across our portfolio.
microagi, whose $55M seed round we backed in July, are keen to capture the same benefits of industrial automation in Europe without having to cede ownership over centuries of factory knowledge to international suppliers. Founded by Bercan Kilic and recently expanding from Munich to London, they’re building an ownable data and deployment layer that will power European industrial robotics.
Autonomous driving has shifted from theoretical to reality over the past few years. Europe awaits its arrival, with Waymo set to launch in London in October. Moove, who announced a $250M Series C in August, will play a central role in bringing autonomous mobility to Europe. Founded by Jide Odunsi and Ladi Delano, their autonomous infrastructure covers fleet ownership, charging, maintenance, and operational orchestration.
Open Cosmos is taking physical AI interstellar, combining an older technology (satellites) with cutting edge intelligence. Their €300M Series C in September is helping cement their status as Europe’s leading satellite manufacturer, as well as strengthening the intelligence layer they’re building around the Earth. Their connected system of satellites is already serving a range of industries (earth observation, connectivity) that understand the growing value in space-based systems.
It’s worth looking beyond Europe too, to see the pace that physical AI companies are racing to match. In the US, Maven Robotics emerged from stealth to launch their general-purpose robotics system for industrial work. Built by former Apple engineer Hamza Derbas and his brother Khalid, they announced a $100M Series A in September. Maven is already well past the concept stage. Its robots are running multiple shifts a day inside a Fortune 250 consumer goods company, and are on track to pass 100,000 hours of real-world autonomous operation by the end of 2026, aiming for 1 million by late 2027.
4. AI enhancing rather than replacing humans remains central to specialist work
Truly autonomous work is starting to flourish in industries with manual, repetitive tasks with clear parameters. But funding this quarter showed that, for industries built on craft, knowledge, and human relationships, human-AI collaboration remains a priority.
Marker is an AI writing companion designed to nurture writing as a craft rather than undo it. Founders Jon Steinback (former Head of Creative & Marketing at DeepMind) and Ryan Bowman (an ex-FT data journalist) were frustrated with writing tools that did the thinking for you. As an antidote, they built a word processor that helps guide your writing without ever taking the pen out of your hand. We’ve backed Marker from the very beginning, and in July they announced their $13M seed round.
From creativity to healthcare, Heidi continued to go from strength to strength in their mission to “double the world’s capacity for care” by placing generative AI and automation into the hands of every clinician. Just two years since launching their AI scribe platform, Heidi now covers 2.8M weekly patient interactions across 190 countries in 110 languages. In September, they announced $340M in new funding to drive their mission.
Poolday is applying a similar idea to video. Its AI agent edits and generates branded video, meaning marketing teams can keep pace with high volume demand. Humans set the brand and the brief, the agent handles the assembly. Founded by Alexei Chemenda and Oliver Nicolini, Poolday raised an $11M seed round in September.
Multiplier, who raised a $35M Series B this August, has embodied this approach for professional services. Rather than build and sell software, founders Noah Pepper and Argyris Zymnis acquire firms and then equip the people within them with AI tooling and technical infrastructure, transforming how they work to supercharge growth and productivity.
Resolutiion has built a new category in risk-to-resolution. Founder Fayola-Maria Jack has built an operating system that observes, resolves, and mitigates commercial disputes that cost enterprises £50-to-90M for every £1BN of contracted revenue under conflict. This September they announced a $10M seed round.
5. Europe raising record-breaking rounds of its own
We know that fundraising doesn’t tell the whole story. But if you believe that Europe still lacks the momentum to build world-leading companies, the numbers tell a very different story.
Mistral’s €3BN Series D was the largest equity round ever raised by a European tech company. That’s significant for a company built by three French engineers and which remains largely headquartered in Paris.
At the earlier end of the spectrum, microagi’s $55M was Germany’s largest ever seed round. That two F1 engineers chose Aachen, then Munich, to build what has become one of Europe’s most promising AI companies shows the viability of homegrown successes.
In the UK, OLIX and CuspAI are showing the sort of breakout success that might have previously been reserved for US companies. OLIX tripled its valuation at its latest fundraise, while CuspAI’s valuation was five times that of its previous round. Again, we know that valuations don’t paint a complete picture, but these moments go some way to demonstrate momentum previously considered a European rarity.
$100M+ fundraises, multi-billion dollar valuations, and exceptional revenue growth feel newsworthy in Europe today. But looking back on Q3, these remarkable achievements feel less remarkable and more inevitable than ever. The future is looking bright after a European summer to remember.
Related reading
23 Sept 2026
British Business Bank commits £50m to Phoenix Court as NatWest joins M&G and HSBC to back platform investing in Britain's scale-ups
Institutional investors join forces to ensure more of the value created by UK innovation benefits Britain Meaningful multi-year partnership across Phoenix Court’s platform, supporting British technology companies across…
22 Sept 2026Written by Saul Klein
Why Britain needs to back Britain
As a serial entrepreneur, operator and investor I’ve noticed that Britain has a habit of talking itself down, even when the evidence tells a different story. Across the…
18 Aug 2026
The New Palo Alto Guidebook: Paris
The New Palo Alto Guidebook takes a trip through the neighbourhoods, cities, and regions that make up Europe’s powerful technology ecosystem. This month, we visit Paris. When Dealroom…
14 Aug 2026Written by Saul Klein
Building Foundations, Planting Seeds: A Chairman's Note
Q1 confirmed the economic engine - a portfolio validated across three clock speeds, our first carried interest distribution, a market moment that vindicated two decades of conviction and…