 Phoenix Court
Building Momentum: A Chairman’s Note
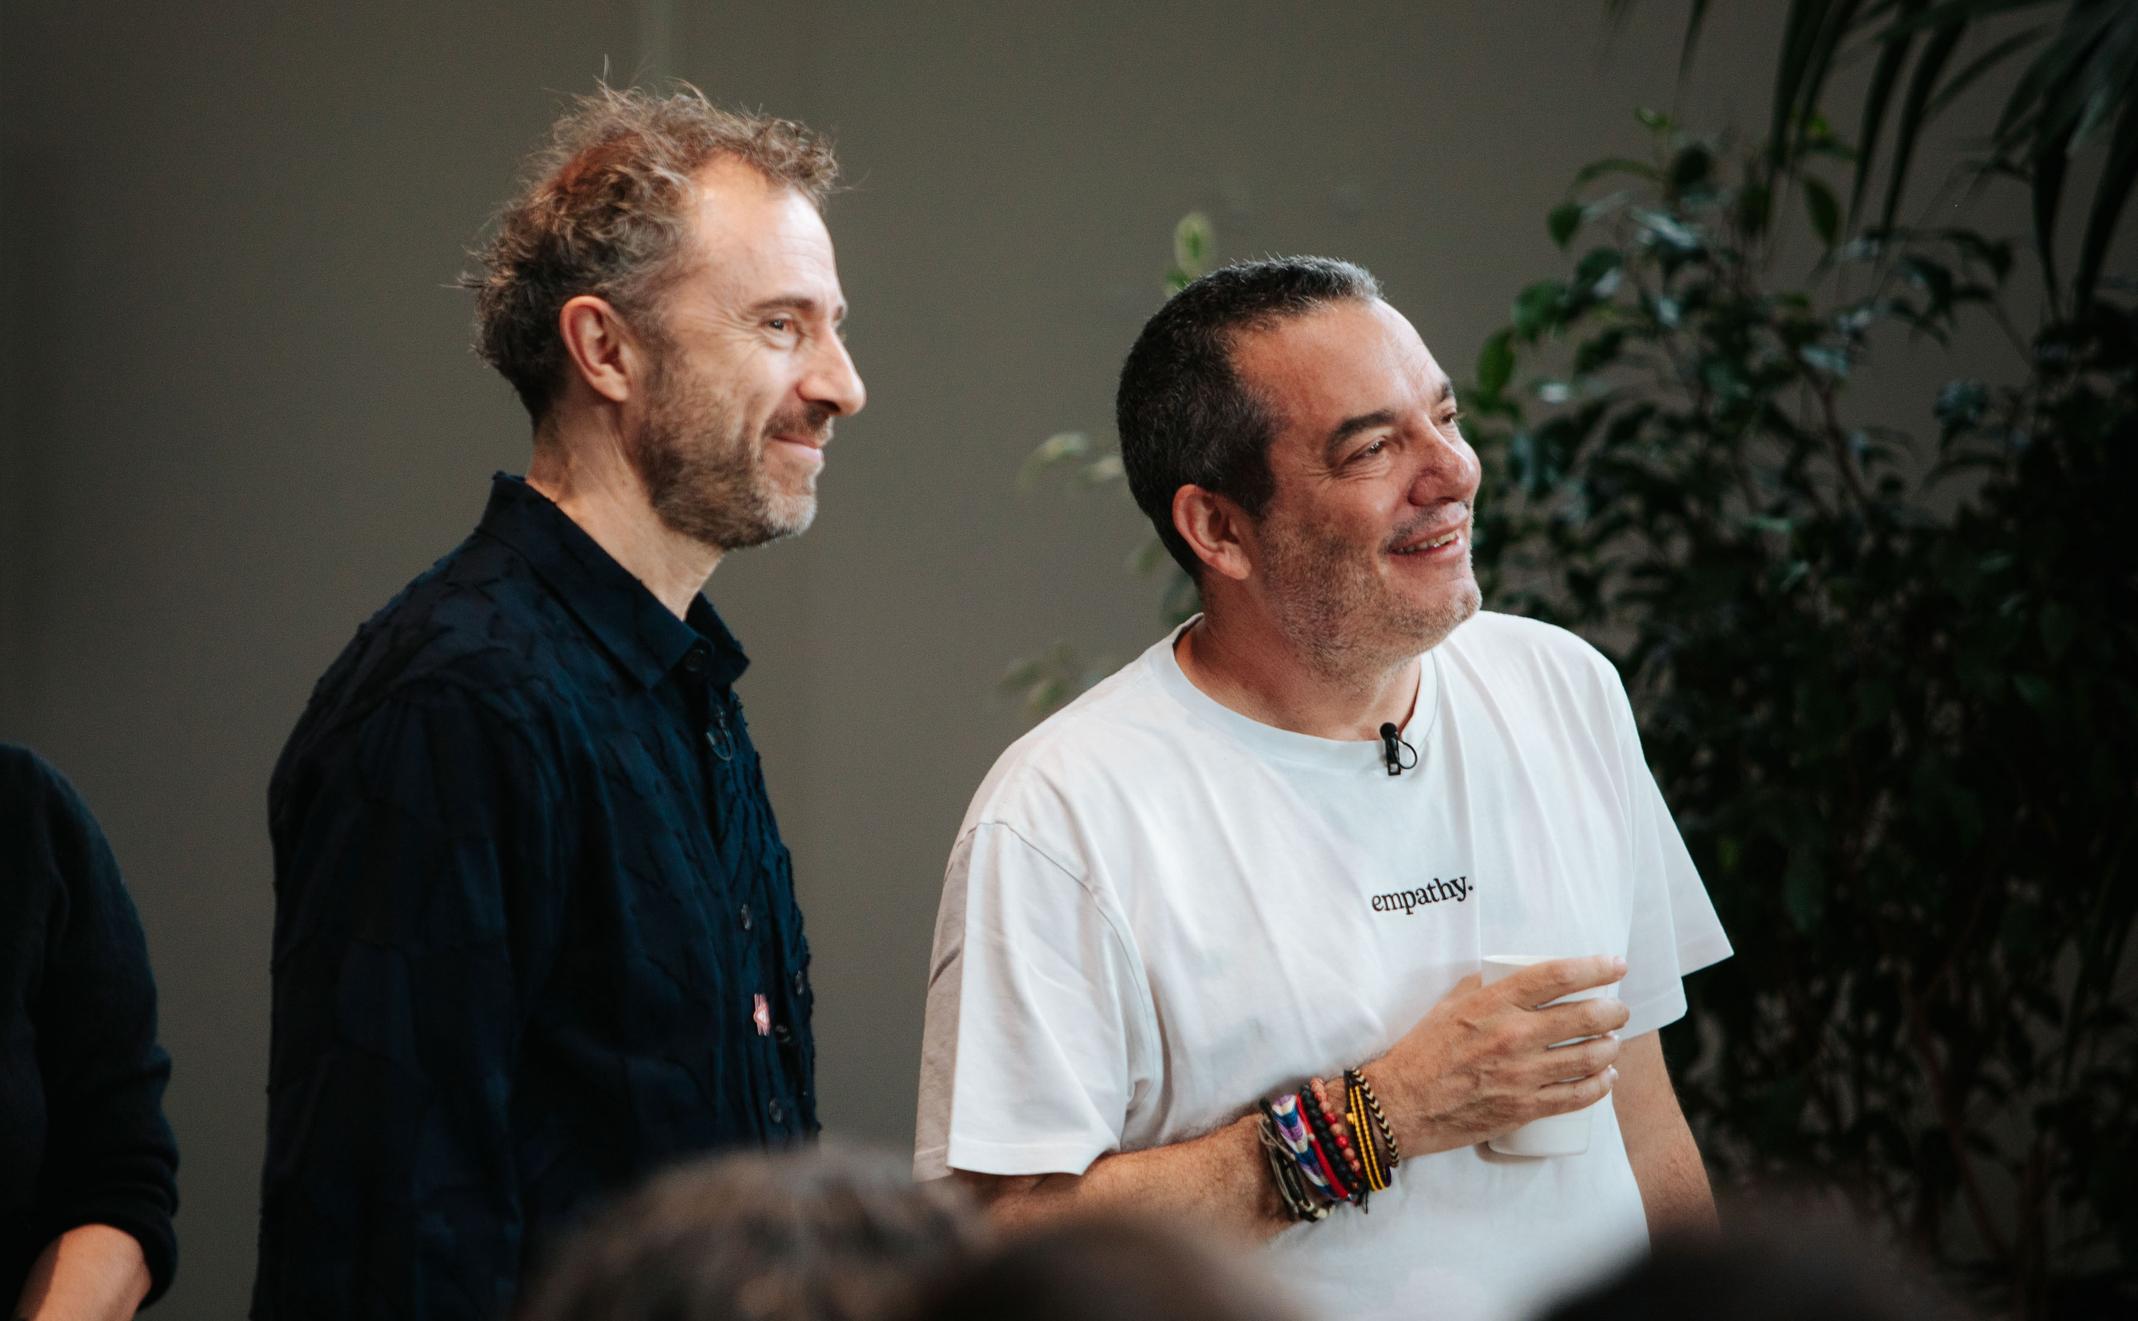 Thomas Heatherwick (left), designer and co-founder of Early, with Saul Klein (right) at our 2026 Annual Showcase.
Ten years ago, UK venture was a $3-4BN a year market with just 18 unicorns.
The prevailing view among investors was that the UK innovation economy would stall and that our market was parochial; a decade on, the picture could not be more different. Annual venture investment has grown sevenfold to $23.6BN, more than Germany, France and Switzerland combined. Britain is now home to more than 200 unicorns and 239 thoroughbreds. Its world-class universities and research institutions produce extraordinary talent, and that talent is attracting the companies building the next frontiers. Today, the UK is the world’s third largest innovation economy behind the US and China, with a tech sector worth $1.3TN, and New Palo Alto is the world’s second largest innovation cluster.
In Q1, we wrote about the engine: Faculty returned our 2015 vintage and we moved to shared ownership. In Q2, we wrote about foundations: putting governance in place and allocating capital, patiently. In Q3, that patient capital started to show momentum: portfolio companies raised $5.5BN in follow-on capital, and some of Britain’s largest institutions became investors across our platform.
As we look ahead to 2027 and the start of our second decade, we are in a strong position built on the same three beliefs we started with:
1. Our geography is a great place to invest. We have long held the conviction that New Palo Alto can generate world-class returns. Q3 gave us more evidence than ever.
2. Investing for the long term in people, platform and infrastructure. We believe that investing in our people, technology, data, AI and physical infrastructure will give us a sustainable competitive advantage, allowing us to consistently make better investments and generate stronger returns over the long term, while maintaining best-in-class governance.
3. Purpose and profit are not mutually exclusive. As well as returning to our investors, we do this while running a profitable technology business that can invest for the long term. Our foundation, Phoenix Court Works, makes over $1.3M of grants each year and is moving to become the firm’s largest shareholder.
Three Clocks, One Summer
Old Palo Alto thinks we switch the lights off in July and August. Not this summer. Our portfolio raised $5.5BN in 90 days.
The fast clock: AI. Mistral’s €3BN Series D was Europe’s largest ever equity round. OLIX tripled its valuation to $3.3BN and CuspAI’s rose 5-fold to $2.7BN. microagi raised Germany’s largest ever seed round and passed $100M of annualised revenue just six months after launching. We also made our first Solar I investment in Heidi, which builds AI that works alongside clinicians, following on from our investment in Latitude III.
The stable clock: revenue-rich. Moove, M-KOPA and HiBob quietly raised growth capital. Moove and M-KOPA have both passed half a billion dollars of revenue run rate, and HiBob’s $166M raise from Salesforce shows the value that continues to accrue to foundational systems of record. In August, I wrote “Nothing to See Here” about these companies: more than 35 businesses, each with over $100M of revenue in unfashionable markets such as SME banking, business travel, used cars, workplace skills and professional services. Motorway demonstrates the pattern, with revenues and margins continuing to climb and targeting cash-positivity this year. Few people write about this clock, but it is where our growth compounds most steadily.
The long clock: science. Open Cosmos became Europe’s leading satellite manufacturer and Nyobolt raised a $60M Series C at a $1.1BN valuation. Across our funds, we’ve made investments in bold categories including cell manufacturing, industrial carbon capture, and solar. Across the platform, we also followed on into Sirona, CoMind and Apollo. These investments move the portfolio further towards parity between software and science.
Britain Backing Britain: A Watershed
As I set out above, Britain has built one of the world’s great innovation economies, with a pipeline of exceptional companies. The opportunity now is at the scale-up stage.
"Britain’s development bank, two of its largest commercial banks and its largest asset manager are backing the UK innovation economy together."
Today, more than 80% of scale-up capital for UK companies comes from overseas. When these companies raise, sell or list abroad, much of the value they create goes to pensioners in Toronto, Copenhagen, and California rather than to UK pensioners. That is changing. We have a generational opportunity to back our very best scale-ups with British capital and keep more of the returns at home.
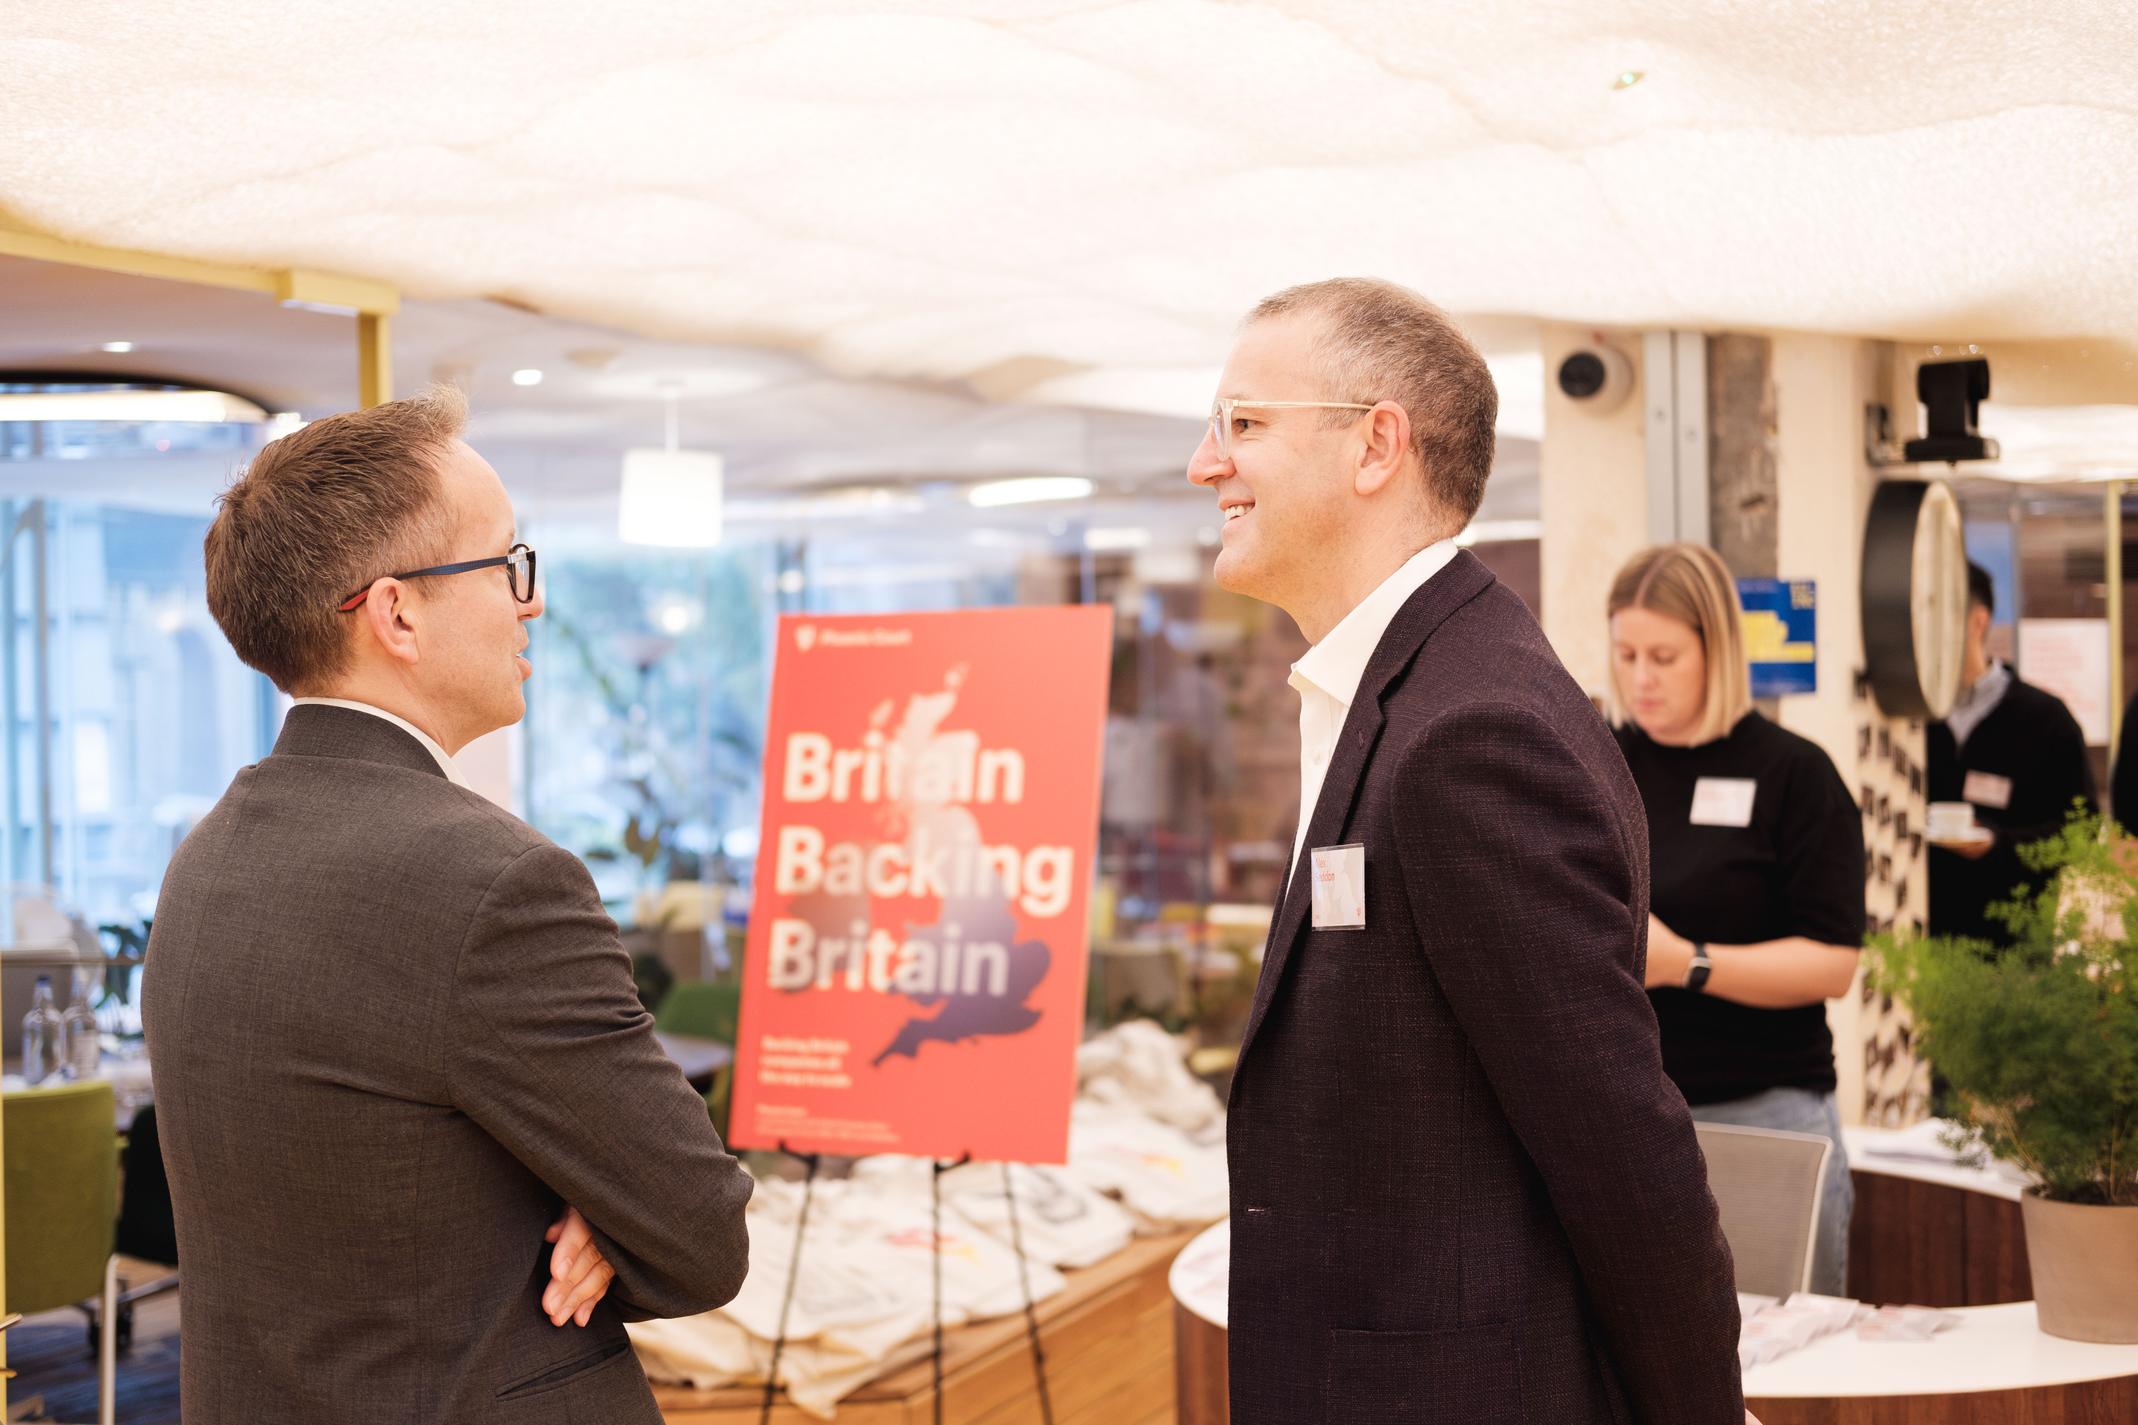 Ian Connatty (left), Managing Partner of British Business Bank's Investment Services, and Alex Seddon, Head of Private Equity at M&G
At our Britain Backing Britain event, we announced long-term partnerships with the British Business Bank and NatWest, alongside continued backing from M&G and HSBC. The BBB made its first investment in Phoenix Court as part of a multi-hundred-million-dollar commitment across our funds. NatWest invested from its balance sheet in Phoenix Court for the first time. M&G built on its anchor commitment to the Solar Pilot. HSBC continued to back us across the funds and through HSBC Innovation Banking.
Britain’s development bank, two of its largest commercial banks and its largest asset manager are backing the UK innovation economy together, through a British platform, with British savers as the beneficiaries. The Solar Pilot shows why: 18 companies, including Tide, Motorway, Monzo, Raspberry Pi, and CuspAI, generating $6.7BN of revenue and 8,500 jobs from Brighton to Edinburgh. As one attendee said to me on the day: we don’t have to shout anymore.
Three Things I Keep Coming Back To
First, the AI trade will correct before it reaches $20 trillion. In Q2 I estimated a drop to $3 trillion ahead of a $10 trillion prize by 2030. A quarter on, I think the correction will be deeper and the prize bigger. October showed us how it starts.
When it emerged that OpenAI’s annualised revenue was nearer $50BN than $70BN, because of how partner sales were accounted for, Nvidia lost $170BN of value in a day. Anthropic’s S-1, filed ahead of a listing expected this month, shows for the first time the true economics behind a frontier AI company. We saw a version of this in 2022. The froth is at the model and infrastructure layer, while durable value accrues to companies using AI to build better, more efficient businesses in very large markets. That is where our fast and stable clocks sit, and we are positioned for both the correction and the growth that follows.
Second, machines are coming for private markets, and finding the signal in the noise with machines and superhumans will set firms apart. You cannot index a venture power law. You have to find outlier founders early and earn the relationship. Of the 20,000 investors Dealroom tracks with a power-law outcome, only 28 have backed more than ten companies from seed to $100M of revenue. We have done it 21 times, number one in EMEA, and thirteenth in the world.
Nazare is how we keep that edge. Six people have joined us this year, including Nuno Campos, our first Head of Technology, who led the creation of LangGraph at LangChain. Nuno is refining and rebuilding Nazare alongside our wider tech stack and strategy. At version 0.4 Nazare is already a trusted member of the team, holding 20,000 companies and 55,000 people with every conviction call logged against its outcome. It also reminds us of our anti-portfolio, the companies we missed, which represent more than $1.3BN of value. Nazare now runs live scans so we keep learning from those misses and improving.
"Finding the signal in the noise with machines and superhumans will set firms apart."
Third, capital alone is no longer enough. As capital becomes commoditised, Venture+ is how we help founders win. Drawing on Nazare’s data, AI and publicly available information, we have identified billions of pounds of UK public-sector contracts across the portfolio. With the BBB, HSBC and NatWest, we are also testing ways to fund growth beyond equity, from contract and export finance to commercial credit. We are now taking what we have learned in the UK to Germany, Japan, and Singapore.
Looking Forward
We go into Q4 with the next cycle under way: four strategies across one platform. LocalGlobe for pre-seed and seed, Latitude for early growth, Solar for scale-up, and Basecamp, our fund of funds for emerging managers and solo GPs. Our investors can continue to utilise our entire platform across all four strategies, as well as starting to leverage our technology and accessing a pipeline of co-investment opportunities.
In October, LPs from more than 30 institutions joined us for our Open House and Annual Showcase. It brought together companies from our first decade and our next, and marked the proper launch of Venture+. Thank you to everyone who came. As always, if you would like a one-to-one conversation, please get in touch.
We have two asks. First, our portfolio companies have raised over $10BN of follow-on funding this year, and we would welcome LPs who want to co-invest alongside us, whether in primary or secondary rounds, directly or through a managed account. If that is of interest, please let us know. Second, if your organisation could be a corporate partner for Venture+, Nin and her team would love to hear from you.
Our first decade built a valuable and diversified book. As machines come for private markets and the best founders look for more than equity, access to the best innovation matters more than ever, for governments and institutions alike. We believe we are well placed to provide it.
Saul Klein
Chair & Co-Founder, Phoenix Court
Related reading
14 Aug 2026Written by Saul Klein
Building Foundations, Planting Seeds: A Chairman's Note
Q1 confirmed the economic engine - a portfolio validated across three clock speeds, our first carried interest distribution, a market moment that vindicated two decades of conviction and…
13 May 2026Written by Saul Klein
Crystallising Our Future: A Chairman’s Note
This is the most consequential quarter we have had as a firm to date. This is easy to write, but it's the result of the compounding of clear…
29 Oct 2026 — editorialWritten by Nin Pandit
How we'll find growth in every postcode
Restoring confidence in the UK economy starts with knowing where the growth is coming from. With the Budget announced this week, we explore the opportunity to capitalise on innovation that already exists around the country.
22 Sept 2026Written by Saul Klein
Why Britain needs to back Britain
As a serial entrepreneur, operator and investor I’ve noticed that Britain has a habit of talking itself down, even when the evidence tells a different story. Across the…